AI and automation should improve the reliability and capacity of the finance function. The implementation starts with the work: information coming in, checks performed, decisions made and records retained. Clear ownership and well-defined processes give technology a useful role in that operating model.
Our approach is to establish the control requirements alongside each workflow. The objective is a finance team that spends less time assembling information and more time reviewing exceptions, understanding performance and supporting decisions.
1. Define the workflow before selecting the tool
Document the source information, required output, accountable owner and points where judgement enters the process. Invoice intake, document collection, approval routing and reporting preparation each need a different design.
Use rules-based automation for work with explicit, testable instructions. Consider AI for tasks involving interpretation, such as extracting information from varied documents or preparing a first draft of commentary. For every proposed use, decide what happens when information is incomplete, contradictory or outside the agreed scope.
2. Establish a trustworthy information path
Define which accounting records, files and policies a workflow may use. Preserve links to source documents and the date information was last updated. For reporting, reconcile the underlying data to the relevant accounting records before asking an AI system to interpret it.
Restrict access to what the task requires. Review the provider's data handling arrangements and configure the approved environment before introducing client information. A finance assistant answering management questions needs an explicit boundary between accessible company information and material it should never retrieve.
3. Keep review and authority visible
Separate preparation from authorisation. A workflow can assemble a payment proposal or draft an accounting entry, with release or posting governed by the approval rules appropriate to that transaction. The person reviewing an output needs the supporting evidence and enough time to assess it.
Define escalation thresholds for unusual amounts, changed supplier details, missing evidence and unresolved exceptions. Record approvals and corrections. Treat human review as a specific control with an owner and evidence of completion.
The NIST AI Risk Management Framework provides voluntary guidance on accountability, evaluation and ongoing risk management across the AI lifecycle. These principles give a useful foundation for assigning operational responsibilities within a finance workflow.
Worked example / Illustrative workflow
A second copy should not become a second payment.
A £1,500 supplier invoice arrives by email, then the same document is uploaded to the shared folder. AI can extract the supplier, invoice number, date and amount from both copies. Extraction alone does not determine whether the invoice should be recorded again.
The workflow checks the legal entity, supplier and invoice reference against existing records. A possible duplicate goes to the accountant’s exception queue. The source documents remain available for review, and posting requires the approved treatment. If the posting request times out, the integration checks whether the first entry was created before retrying.
The control outcome is specific: one approved invoice produces one accounting entry. The accountant resolves ambiguous matches; a separate authorised approver controls payment release.
This is an illustrative control design, not a claim about a measured client result or a live integration running on this website.
4. Test the exceptions as well as the routine work
Before release, test the workflow against representative examples, including duplicate invoices, incomplete documents, currency differences and unexpected formats where relevant. Compare outputs with independently checked results.
Agree what constitutes an acceptable result, which exceptions must stop the workflow and who authorises deployment. Retain the test evidence. After a material change to a model, integration or accounting process, repeat the checks affected by that change.
5. Manage the process after implementation
Assign someone to monitor failures, review exceptions and maintain documentation. Make it possible to pause the workflow and continue essential finance work through a documented fallback. Track the measures that matter to the process: correction rates, unresolved exceptions, review time and completion against the reporting timetable.
Start with one defined workflow, establish its baseline and expand once the team can operate and maintain it confidently. At BriQs Group, AI and automation are embedded in our fractional CFO service and complete finance department. Our approach develops the systems and controls while the team runs the daily function.
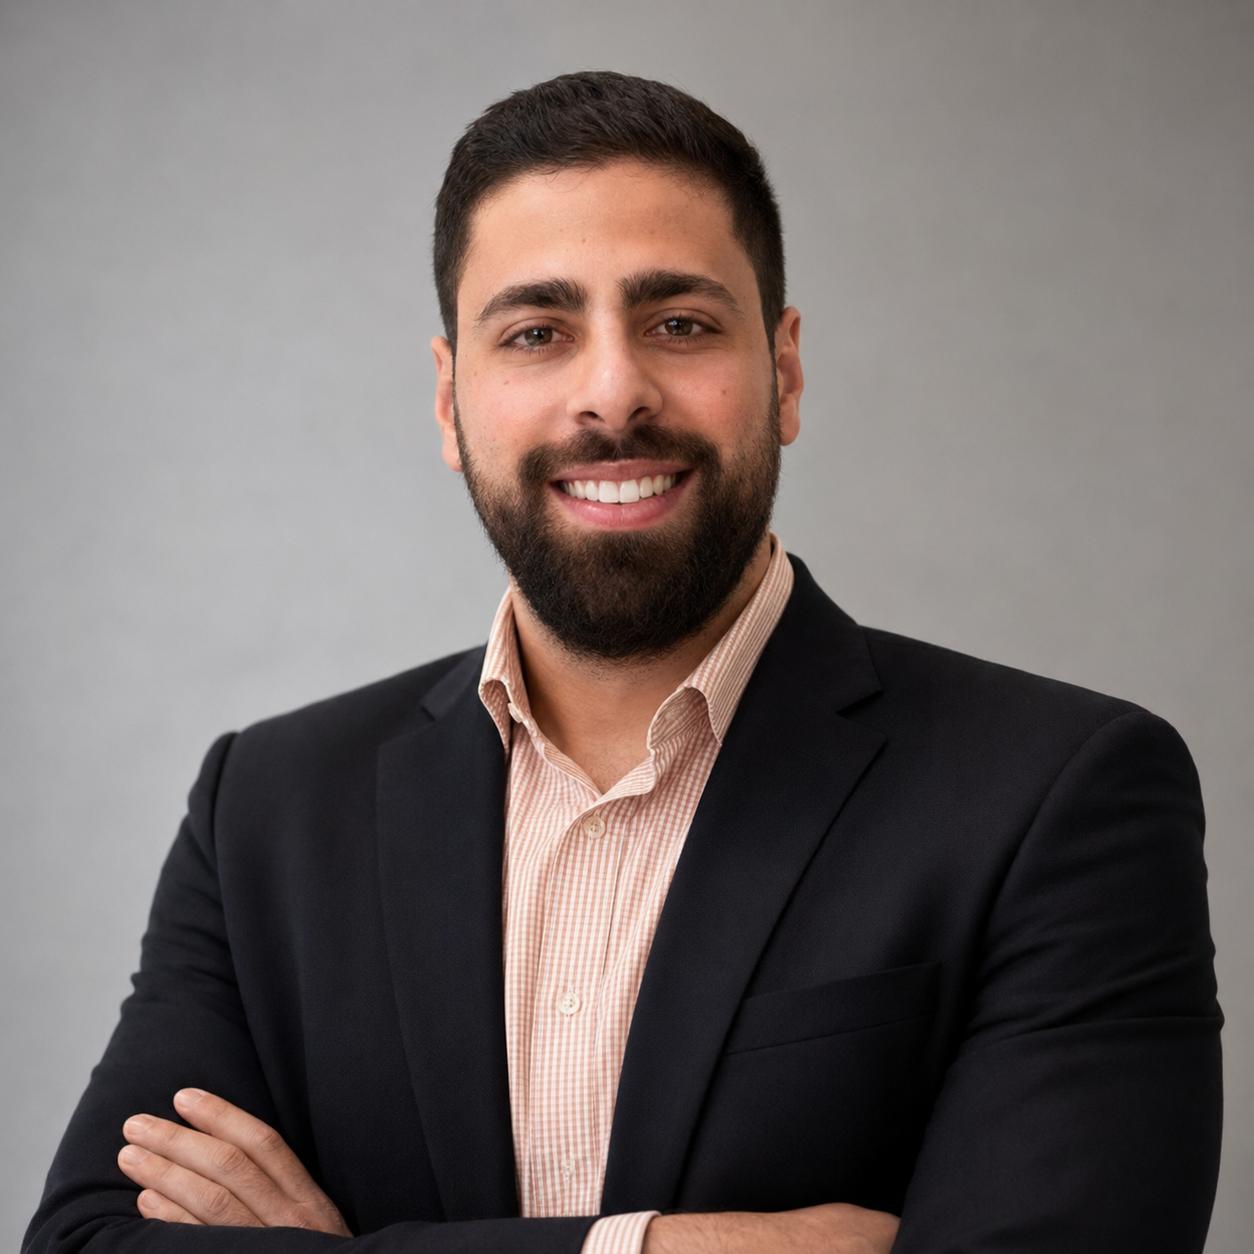
Founder & CEO, BriQs Group. More than ten years at Big Four accounting firms, followed by building BriQs’ finance methodology for startups and SMEs.
Read Sanad’s profile